


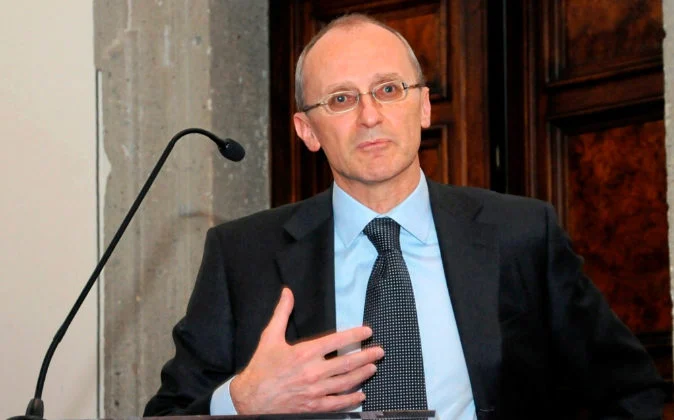
Speaking at the Copenhagen Business School, Andrea Enria, the Chairman of the European Banking Authority (EBA), has formally challenged the prevailing regulatory sentiments of his international peers regarding the digital asset and financial technology sectors. Addressing a specialized seminar on Fintech, Enria articulated a vision that moves away from what he described as "sub-optimal" binary choices, instead proposing a nuanced, middle-ground approach that prioritizes both innovation and financial stability. His remarks come at a pivotal moment for the European Union as it seeks to harmonize its digital finance strategy across the Single Market.
Enria criticized the "Manichean" approach that currently dominates the global discourse on cryptocurrency regulation. According to the EBA chief, authorities are largely divided into two unproductive camps. The first position, "regulate and restrict," seeks to prohibit or heavily constrain any financial initiative that deviates from traditional, established standards. The second position, a "laissez-faire" or "let things happen" approach, suggests that all operations should be permitted, leaving the risks entirely on the shoulders of the participants involved. Enria argued that both extremes fail to serve the public interest or the health of the financial ecosystem.
The "regulate and restrict" mindset, Enria noted, creates a significant barrier to entry for startups. By imposing the same heavy regulatory burdens on small, innovative firms that are applied to systemic global banks, authorities risk stifling the capitalization of crypto-based activities and diminishing the chances of success for new market entrants. Conversely, the "laissez-faire" approach creates a "Wild West" environment where the lack of legal certainty and consumer protection can actually deter institutional capital. Investors, he argued, will always seek at least a reasonable level of legal protection before committing significant resources to a sector.
The Functional Approach to Financial Supervision
Central to Enria’s argument is the concept of functional segmentation. He suggested that not all financial activities require the same level of oversight. Instead of a blanket regulatory perimeter that captures all fintech firms under bank-like supervision, Enria proposed a tiered system based on the nature of the services provided.
"Andrea Enria thinks certain functions, such as providing liquidity in crisis situations and lending, should be reserved for the banks and subject to enhanced regulation and supervision," the Chairman noted during his presentation. These core functions are inherently systemic; a failure in the banking sector’s ability to provide credit or liquidity can lead to broader economic collapse. Therefore, these areas must remain under the strictest watch of the EBA and other national competent authorities.
However, Enria argued that other services—specifically those involving payments and the issuance of electronic money—do not necessarily carry the same systemic risks. Because these services are not intrinsically tied to the essential, stability-preserving functions of banks, they should be open to a wider range of intermediaries. Enria cautioned that an "excessive extension of the regulatory perimeter" would likely be a sub-optimal solution. By forcing every fintech firm to adhere to the exhaustive requirements of a banking license, regulators might inadvertently crush the very innovation they seek to foster. "In these areas of business, we may well let innovators experiment with new products and business practices," he added.
Technological Neutrality and the Fight Against Status Quo Bias
A recurring theme in Enria’s speech was the need for "technological neutrality" in lawmaking. This principle holds that regulations should focus on the activity being performed rather than the technology used to perform it. Whether a payment is processed via a traditional ledger or a distributed blockchain should be secondary to the regulatory objective of ensuring the transaction is secure, transparent, and compliant with anti-money laundering (AML) standards.
Enria called for a "proportionate" approach to combat the inherent bias toward the status quo. In many jurisdictions, the regulatory framework is built around the legacy infrastructure of the 20th century, which creates a natural disadvantage for digital-first companies. By advocating for a proportionate and neutral framework, the EBA seeks to bridge the gap between radical proponents of decentralization and conservative defenders of traditional banking.
This stance is reflected in the EBA’s broader strategy. To ensure that regulations remain on the right track, the authority has developed a comprehensive "Fintech Roadmap." This roadmap is designed to allow fintech firms to scale their operations across the European Single Market more effectively. By providing a unified set of rules, the EBA aims to eliminate the "fragmentation" that currently forces startups to navigate 27 different sets of national regulations, thereby providing benefits to all EU citizens through increased competition and lower costs.
Historical Context: The 2018 Regulatory Landscape
To understand the significance of Enria’s remarks, one must look at the state of the financial markets at the time of his speech. In early 2018, the cryptocurrency market was reeling from the volatility of the previous year’s "bull run," which saw Bitcoin reach near $20,000 before a sharp correction. This volatility had prompted many global regulators—including those in the United States, China, and South Korea—to call for aggressive crackdowns.
In the United States, the Securities and Exchange Commission (SEC) was beginning to ramp up its scrutiny of Initial Coin Offerings (ICOs), frequently asserting that most digital tokens were unregistered securities. In Asia, China had already moved to ban cryptocurrency exchanges and ICOs entirely, citing concerns over financial stability and capital flight.
Against this backdrop, Enria’s speech represented a distinctly European "third way." While the ECB (European Central Bank) had expressed concerns about the risks of "crypto-assets," Enria’s EBA focused on the potential for fintech to modernize the European economy. The EBA’s mandate, established in 2010 in the wake of the global financial crisis, was to ensure effective and consistent prudential regulation across the European banking sector. Enria, who served as the first Chairman of the EBA from 2011 until late 2018, was instrumental in shaping this mandate to include the oversight of emerging financial technologies.
The EBA Fintech Roadmap: A Timeline of Progress
The Copenhagen speech followed the official publication of the EBA’s "Roadmap on Fintech" in March 2018. This document outlined the authority’s priorities for the coming years, including:
- Monitoring the Regulatory Perimeter: Assessing whether current EU laws are sufficient to cover new business models like crowdfunding and peer-to-peer lending.
- Cybersecurity and Resilience: Establishing common standards for how financial institutions manage IT risks and protect against cyberattacks.
- Consumer Protection: Ensuring that digital financial products are transparent and that consumers are not misled by the complexities of crypto-assets.
- Anti-Money Laundering (AML): Integrating fintech firms into the existing framework of the 5th Anti-Money Laundering Directive (5AMLD) to prevent the financing of terrorism and illicit activities.
Enria’s advocacy for "scaling up" across the Single Market was a direct response to the "passporting" issues faced by startups. In the EU, "passporting" allows a firm authorized in one member state to provide services in any other member state without needing further authorization. Enria argued that applying this principle more effectively to fintech would create a truly pan-European digital economy.
Industry Reactions and Implications
The reaction to Enria’s "pragmatic" stance has been largely positive within the fintech community. Industry advocates have long argued that "one-size-fits-all" regulation favors large incumbents who have the legal and financial resources to comply with complex rules, effectively creating a "regulatory moat" that keeps out smaller competitors.
Conversely, some traditional banking associations have expressed concerns about "regulatory arbitrage." They argue that if fintech firms are allowed to provide banking-like services with lower regulatory requirements, it could lead to an unlevel playing field. Enria addressed this by reiterating that "core" functions—those that define a bank’s role in the economy—would remain strictly protected and heavily regulated.
From a broader economic perspective, Enria’s approach suggests a shift toward "regulatory sandboxes." These are controlled environments where startups can test new products under the supervision of regulators without being subject to the full weight of the law. This allows regulators to understand the risks of new technology in real-time, while giving firms the room to innovate.
Analysis: The Future of European Digital Finance
The implications of Enria’s Copenhagen address extend far beyond 2018. His vision laid the groundwork for what would eventually become the Markets in Crypto-Assets (MiCA) regulation, the EU’s comprehensive framework for digital assets. By championing the ideas of proportionality and technological neutrality early on, Enria helped position Europe as a leader in digital finance regulation—a region that seeks to be "pro-innovation" without sacrificing "pro-stability" values.
The "middle path" advocated by Enria recognizes that the digital revolution in finance is inevitable. Attempting to stop it through prohibition is likely to drive innovation underground or to other jurisdictions, while ignoring it could lead to a repeat of the systemic failures seen in 2008. By focusing on the function of the service and the proportionality of the risk, the EBA under Enria’s leadership sought to create a sustainable environment where the next generation of financial giants could emerge within a safe and regulated framework.
As the financial world continues to grapple with the rise of Decentralized Finance (DeFi), stablecoins, and Central Bank Digital Currencies (CBDCs), the principles laid out by Andrea Enria at the Copenhagen Business School remain highly relevant. The balance between allowing "innovators to experiment" and maintaining "enhanced supervision" over systemic functions continues to be the primary challenge for regulators worldwide. For the EBA, the goal remains clear: to foster a competitive, integrated, and secure financial market that serves the interests of all European citizens.














