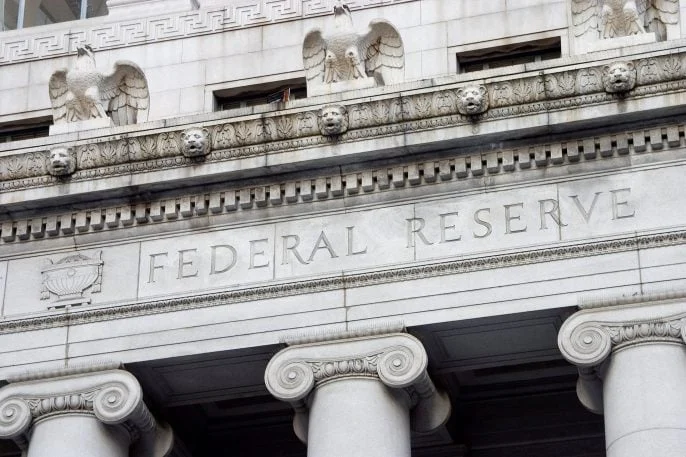
The Federal Open Market Committee (FOMC) released the minutes from its September 15–16 meeting on Wednesday, signaling a hawkish stance that suggests the central bank is far from finished with its campaign against inflation. According to the internal records, a majority of Federal Reserve officials believe that at least one more interest rate increase will likely be necessary before the conclusion of the year. This sentiment is driven by a combination of stubbornly persistent inflation and an unexpected surge in economic demand linked to the massive buildout of artificial intelligence (AI) infrastructure.
The minutes provide a granular look at the discussions that led to the unanimous decision in September to raise the federal funds target range by 25 basis points, bringing it to 3.75% to 4%. While the labor market continues to show signs of strength, the central bank remains concerned that the path back to its 2% inflation target is more arduous than previously anticipated. The documents highlight a growing consensus that the risks to inflation remain "tilted to the upside," requiring a "higher for longer" approach to monetary policy that could extend well into the latter half of the decade.
The September Decision and Unanimous Support
The September meeting was characterized by a rare level of internal agreement regarding the immediate path of interest rates. All participants voted in favor of the quarter-percentage-point increase, a move that reflected the committee’s dedication to cooling an economy that has remained surprisingly resilient in the face of previous tightening cycles. Policymakers noted that while the economy has absorbed significant rate hikes over the past 18 months, the underlying momentum in consumer spending and business investment has not waned sufficiently to guarantee a return to price stability.
Officials generally judged that the labor market was operating at or near full employment. However, this strength is viewed as a double-edged sword. While it supports household incomes and prevents a hard landing, it also contributes to wage growth that, if not matched by productivity gains, could keep service-sector inflation uncomfortably high. The minutes revealed that several officials are watching for signs of "labor hoarding," where firms remain reluctant to lay off workers despite slowing demand, potentially delaying the necessary cooling of the economy.
The AI Infrastructure Boom as an Inflationary Catalyst
Perhaps the most striking revelation from the September minutes was the prominence of the artificial intelligence sector in the Fed’s economic assessment. For the first time in recent history, policymakers explicitly cited the "AI buildout" as a significant factor in both current price pressures and future demand forecasts. The surging investment in AI infrastructure—ranging from the construction of massive data centers to the procurement of high-end semiconductors—is creating a new layer of demand that may be outstripping the economy’s productive capacity.
Some officials warned that this technological gold rush could push demand above supply over the medium term. This is not merely a tech-sector phenomenon; the buildout requires enormous amounts of energy, specialized construction materials, and high-skilled labor. Business contacts reported to the Fed that the costs associated with these projects are rising rapidly. More importantly, participants noted that companies involved in the AI supply chain appear increasingly able to pass these cost increases along to their customers, a classic sign of inflationary pressure.
The AI investment boom is also being felt in the credit markets. During the period between the August and September meetings, Treasury yields rose roughly 35 basis points across maturities ranging from two to ten years. Market commentary reviewed by the Fed cited heavy corporate and government borrowing to finance AI-related infrastructure as a primary driver of these higher yields. This suggests that the "AI effect" is not just a driver of GDP growth, but is also contributing to a higher "natural" rate of interest, complicating the Fed’s efforts to reach a restrictive policy stance.
Inflation Persistence and the 2% Target
Despite the Fed’s aggressive tightening over the past year, the minutes showed broad concern that inflation has made "insufficient progress" toward the 2% mandate. Fed staff provided updated estimates showing that annual headline Personal Consumption Expenditures (PCE) inflation reached 3.8% in August, while the core PCE—which strips out volatile food and energy costs—stood at 3.4%.
The meeting also touched on technical adjustments to these figures. Under a forthcoming change to the Bureau of Economic Analysis (BEA) methodology, these estimates would be revised slightly downward to 3.6% for headline and 3.2% for core inflation. However, policymakers emphasized that even with these adjustments, inflation remains significantly above the target. The persistence of high energy prices, exacerbated by ongoing geopolitical tensions in Eastern Europe and the Middle East, continues to pose a risk of "second-round effects" where higher energy costs seep into the prices of other goods and services.
The staff’s internal projections have become increasingly conservative regarding the timeline for price stability. Fed economists raised their inflation forecasts for the 2026–2028 period and now project that headline inflation will not return to the 2% target until 2029. This extended timeline suggests that the "last mile" of the inflation fight may be the most difficult, requiring the central bank to maintain a restrictive stance for a much longer period than the markets currently expect.
Financial Conditions and Market Resilience
One of the more complex debates during the September meeting centered on whether current interest rates are actually "restrictive." Several officials argued that the policy rate is currently either "not restrictive or only mildly restrictive," citing the fact that financial conditions remain relatively loose despite the nominal increase in the federal funds rate.
While Treasury yields have climbed, many officials pointed out that strong equity prices and narrow corporate credit spreads have helped offset the impact of higher borrowing costs. This "wealth effect" from a buoyant stock market can support consumer spending, potentially neutralizing the Fed’s attempts to slow the economy. Conversely, the housing market remains the one area where the Fed’s policy is clearly having an impact; elevated mortgage rates continue to weigh heavily on home sales and construction activity.
The minutes noted that many participants believe a higher rate path is necessary as "insurance" against the risk of inflation becoming embedded in the public’s expectations. There is a palpable fear among policymakers of repeating the mistakes of the 1970s, where the Fed eased policy too early, only to see inflation roar back with greater intensity.
Chronology of the Tightening Cycle
To understand the weight of the September minutes, it is essential to view them within the broader timeline of the Federal Reserve’s recent actions. After keeping rates near zero for much of the pandemic recovery, the Fed began its tightening cycle in March 2022.
- March 2022 – January 2023: The Fed engaged in a series of aggressive hikes, including several 75-basis-point increases, as CPI inflation peaked above 9%.
- Spring 2023: The pace of hikes slowed to 25 basis points as the committee sought to assess the "lagged effects" of its policy.
- June 2023: The Fed implemented a "hawkish pause," holding rates steady but signaling that more hikes were coming.
- September 2023: The unanimous 25-basis-point hike to the 3.75%–4.00% range, accompanied by the minutes released today.
This chronology illustrates a shift from a "sprint" to a "marathon." The September minutes confirm that the central bank is now in a phase of "fine-tuning," where the data from specific sectors—like AI and energy—takes on greater importance than aggregate national figures.
Broader Economic Implications and Global Reactions
The Fed’s stance has immediate and profound implications for the global economy. As the U.S. central bank signals a higher-for-longer rate environment, the U.S. dollar is expected to maintain its strength against major currencies. This poses a challenge for emerging markets, which often carry debt denominated in dollars and may face increased capital outflows as investors chase higher yields in the United States.
Domestically, the emphasis on AI as an inflationary driver suggests a shift in how the Fed views technological progress. Traditionally, technological advancement is seen as deflationary because it increases productivity. However, the Fed’s current view is that the investment phase of AI is currently inflationary because of the massive resources it consumes before those productivity gains are actually realized.
Economists and market analysts have reacted to the minutes with a mixture of caution and validation. Many had already suspected that the Fed was concerned about the AI boom’s impact on the bond market. "The Fed is acknowledging a new reality where traditional manufacturing and housing aren’t the only drivers of the business cycle," said one senior market strategist. "The massive capital expenditure in tech is providing a floor for economic growth that the Fed is finding very difficult to crack."
Conclusion: Looking Ahead to October
The minutes conclude by emphasizing that the path forward is not set in stone. Officials were careful to state that another rate hike is "not predetermined" and will depend entirely on the incoming data and the evolving balance of risks. The next policy meeting, scheduled for October 27 and 28, will be a critical juncture.
Between now and then, the committee will be looking for signs of cooling in the labor market and a deceleration in core PCE inflation. However, if the AI-driven investment surge continues to prop up demand and energy prices remain volatile, the "insurance" of a year-end rate hike may become a certainty. For now, the Federal Reserve has sent a clear message to the markets: the battle against inflation is entering a new, more complex phase, and the era of low interest rates is firmly in the rearview mirror.