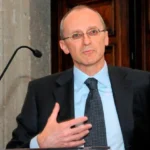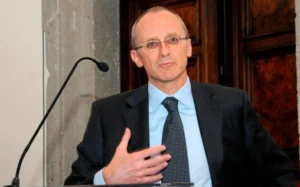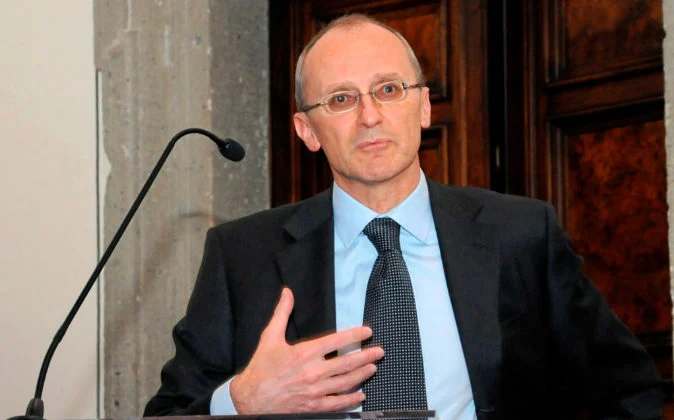
The Chairman of the European Banking Authority (EBA), Andrea Enria, has formally voiced his opposition to the increasingly polarized approaches to cryptocurrency and FinTech regulation, advocating instead for a pragmatic "middle way" that balances innovation with financial stability. Speaking at a high-level seminar hosted by the Copenhagen Business School, Enria addressed the growing debate among global financial authorities regarding how to integrate emerging digital asset markets into the existing financial architecture. His remarks come at a critical juncture for the European Union as it seeks to define its position in the global digital economy while maintaining the integrity of its banking sector.
Enria’s address focused on the "sub-optimal" nature of the current regulatory discourse, which he characterized as being trapped in a Manichean struggle between two extreme ideologies. The first, which he termed the "regulate and restrict" approach, seeks to subject all new financial technologies to the same rigorous standards as traditional banking, effectively stifling the growth of startups and decentralized initiatives. The second, the "laissez-faire" approach, argues for a hands-off policy where markets are left to self-regulate and participants bear all risks individually. Enria argued that neither of these paths serves the long-term interests of the European Single Market or its citizens.
The Critique of Regulatory Extremes
In his analysis, Enria detailed the specific failures of the binary positions currently dominating the policy landscape. The "regulate and restrict" camp, he argued, creates a barrier to entry that prevents capitalization of crypto-based activities and limits the competitive pressure that FinTech firms can apply to traditional banks. By imposing an "excessive extension of the regulatory perimeter," authorities risk forcing innovators into a mold that does not fit their business models, thereby diminishing the chances of success for the very firms that could modernize the European financial system.
Conversely, the "laissez-faire" or "let things happen" approach presents a different set of dangers. Enria noted that a lack of regulation leads to an increase in systemic risks and fails to provide the legal protection necessary to attract institutional capital. He emphasized that serious investors and mainstream financial actors require a "reasonable level of legal protection" and a predictable regulatory environment before they can commit significant resources to the digital asset space. Without a formal framework, the market remains volatile and prone to manipulation, which ultimately harms the broader economy.
Defining the Regulatory Perimeter: Core vs. Non-Core Functions
Central to Enria’s proposal is a functional distinction between what constitutes a "bank" and what constitutes a "financial service provider." He argued that the regulatory perimeter should be drawn based on the nature of the activity rather than the technology used. Under this vision, certain core functions—specifically the provision of liquidity during crisis situations and the act of lending—should remain the exclusive domain of traditional banks. These institutions, Enria asserted, must continue to be subject to "enhanced regulation and supervision" because their failure poses a systemic threat to the global economy.
However, Enria made a clear distinction for services that do not carry the same level of systemic risk, such as payment processing and the issuance of electronic money. He argued that these functions are not "intrinsically related to the essential functions of banks" and should therefore be open to a wider range of intermediaries, including FinTech startups and cryptocurrency firms. By allowing these innovators to experiment with new products and business practices in a less restrictive environment, the EBA aims to foster a more dynamic financial ecosystem.
The EBA FinTech Roadmap and Technological Neutrality
To operationalize this vision, the EBA has developed a comprehensive roadmap designed to guide the integration of FinTech into the European market. A key pillar of this roadmap is the principle of "technological neutrality." This approach dictates that regulations should be designed to address specific risks and outcomes rather than targeting specific technologies like blockchain or distributed ledger technology (DLT). By remaining neutral, lawmakers can ensure that the legal framework remains relevant even as technology evolves, preventing a built-in bias toward the status quo.
The EBA’s roadmap focuses on several critical areas:
- Monitoring the Perimeter: Continuously assessing whether new activities should fall under banking regulations.
- Authorizing and Scaling: Creating a path for FinTech firms to scale their operations across the EU Single Market, utilizing "passporting" rights that allow a firm authorized in one member state to operate across the entire union.
- Cyber Resilience: Ensuring that as the financial system becomes more digitized, it remains protected against sophisticated cyber threats.
- Consumer Protection: Establishing baseline protections for users of digital assets without imposing the full weight of traditional banking compliance on every small-scale service provider.
Historical Context: The 2018 Regulatory Climate
Enria’s statements in Copenhagen reflect the broader shifts occurring in the global financial landscape throughout 2018. This period followed the unprecedented "crypto boom" of late 2017, which saw the market capitalization of digital assets skyrocket, followed by a significant correction. This volatility prompted a wave of reactionary calls for bans or heavy-handed restrictions from central banks in Asia and North America.
In Europe, the response has been more measured but fragmented. While some nations, such as Switzerland and Malta, moved quickly to establish "crypto-friendly" jurisdictions, others remained skeptical. Enria’s role as the head of the EBA is to harmonize these disparate views into a unified European strategy. His call for a "proportionate" approach is seen as an attempt to prevent a "race to the bottom" where member states compete by lowering standards, while also preventing a "regulatory chill" that would see Europe lose its competitive edge to Silicon Valley or Singapore.
Implications for Startups and Traditional Institutions
The pragmatic approach advocated by Enria has significant implications for both the burgeoning FinTech sector and established financial institutions. For startups, the EBA’s stance offers a glimmer of hope that they will not be regulated out of existence before they can reach maturity. By allowing for "experimentation," the EBA is effectively endorsing the concept of regulatory sandboxes, where firms can test new products under the watchful eye of supervisors without the immediate burden of full compliance.
For traditional banks, Enria’s comments serve as both a protection and a warning. While he defends their "essential functions" and ensures they are not undercut by unregulated competitors in the lending and liquidity space, he also makes it clear that banks can no longer rely on regulatory barriers to protect their dominance in the payments and e-money sectors. This encourages traditional banks to either innovate internally or partner with FinTech firms to maintain their market share.
Analysis of Potential Long-Term Impact
If Enria’s vision is successfully implemented across the European Union, it could set a global precedent for how modern economies handle the digital transformation of finance. A proportionate, functional, and technologically neutral framework would likely lead to:
- Increased Institutional Adoption: Legal clarity is the primary requirement for hedge funds, pension funds, and insurance companies to enter the crypto market. A balanced framework provides the "legal protection" Enria highlighted as essential.
- Enhanced Consumer Choice: By lowering the barriers for payment providers, EU citizens could benefit from lower transaction fees, faster cross-border payments, and more diverse financial products.
- Systemic Stability: By keeping the "enhanced supervision" focused on core banking functions, the EBA ensures that the volatility of the crypto markets does not spill over into the essential lending and liquidity mechanisms that keep the real economy functioning.
However, the path to implementation remains fraught with challenges. Achieving consensus among all EU member states, each with their own national interests and levels of technological adoption, is a monumental task. Furthermore, the rapid pace of innovation in decentralized finance (DeFi) may move faster than the EBA’s ability to update its "proportionate" rules.
Conclusion
Andrea Enria’s address at the Copenhagen Business School represents a sophisticated evolution in the regulatory philosophy surrounding digital assets. By rejecting the "Manichean" choice between total control and total freedom, the EBA is attempting to carve out a space where innovation can flourish within a framework of safety and stability. As the EBA continues to roll out its FinTech roadmap, the global financial community will be watching closely to see if this "middle way" can indeed provide the benefits of the digital revolution to all EU citizens while safeguarding the bedrock of the financial system. The success of this approach will ultimately depend on the ability of regulators to remain as agile and forward-thinking as the technologies they seek to oversee.