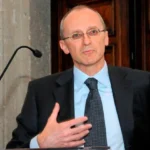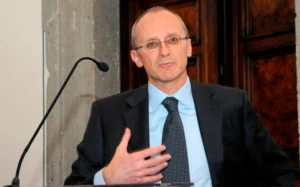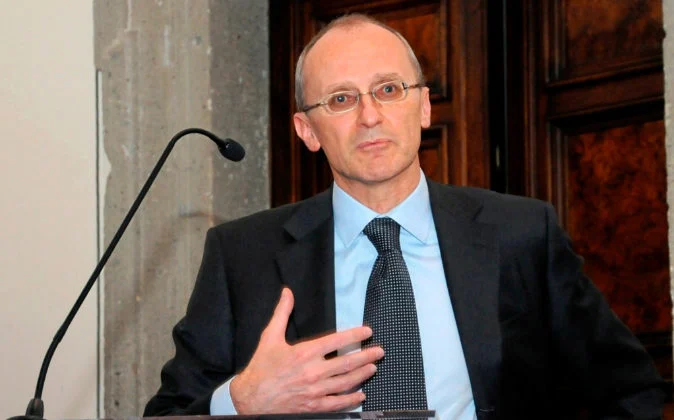
Speaking before an audience of academics, industry leaders, and students at the Copenhagen Business School, Andrea Enria, the Chairman of the European Banking Authority (EBA), has articulated a nuanced vision for the future of financial regulation in the age of digital assets. In a significant departure from the more restrictive rhetoric adopted by several of his global counterparts, Enria argued that imposing excessive or blanket regulations on cryptocurrency markets and fintech startups would be a "sub-optimal" solution for the European economy. His address, delivered during a period of heightened volatility and regulatory scrutiny in the crypto sector, sought to bridge the gap between innovation and consumer protection, advocating for a framework that acknowledges the unique nature of decentralized technologies while maintaining the integrity of the traditional banking system.
Enria’s critique centered on what he described as a "Manichean approach" currently dominating the discourse among global financial authorities. This binary debate, according to the EBA chief, typically pits two extreme positions against one another. The first position, characterized as "regulate and restrict," seeks to force all new financial initiatives into existing, rigid regulatory boxes or to prohibit any activity that deviates from established institutional standards. Enria warned that such a heavy-handed approach risks stifling the growth of the nascent fintech sector, as startups would face insurmountable compliance costs and capitalization hurdles before their products could even reach the market. By limiting the ability of firms to utilize crypto-asset-based capitalization, regulators might inadvertently kill off the very innovations that could modernize the European financial landscape.
The second position, often referred to as "laissez-faire" or "let things happen," posits that the digital asset market should remain largely unregulated, with all risks borne exclusively by the participants involved. Enria was equally critical of this stance, noting that a complete lack of oversight creates a "Wild West" environment that ultimately discourages institutional investment. He argued that serious capital—the kind required to scale technology across the European Single Market—will always gravitate toward environments that offer at least a baseline of legal certainty and consumer protection. Without a clear regulatory perimeter, the risks associated with non-regulated markets could become systemic, potentially leading to a loss of public trust in the broader financial ecosystem.
Defining the Regulatory Perimeter and Banking Functions
At the heart of Enria’s proposal is a pragmatic distinction between the essential functions of traditional banking and the specialized services provided by fintech intermediaries. He argued that certain core activities, specifically the provision of liquidity during crisis situations and the act of lending, are so fundamental to financial stability that they must remain the exclusive domain of licensed banks. These functions, Enria asserted, should be subject to "enhanced regulation and supervision" to prevent the kind of systemic collapses seen during the 2008 financial crisis. By keeping these "essential functions" under strict oversight, regulators can ensure that the backbone of the economy remains resilient.
Conversely, Enria suggested that other financial services—such as payment processing, the issuance of electronic money, and currency exchange—do not inherently require the same level of intensive, bank-like supervision. He noted that these services are not intrinsically linked to the high-risk liquidity cycles of the traditional banking sector. Therefore, allowing fintech firms and crypto-based startups to operate in these areas with a more flexible regulatory burden would encourage experimentation and competition. "An excessive extension of the regulatory perimeter, attracting most fintech firms under the scope of bank-like supervision just because they compete with banks in some market segment, is likely to be a sub-optimal solution," Enria stated. He emphasized that in these specific business segments, innovators should be given the room to test new products and business models without being crushed by the weight of legacy banking laws.
Technological Neutrality and the Fight Against Status Quo Bias
A cornerstone of Enria’s philosophy is the concept of "technological neutrality." He called for the development of laws that are proportionate to the risks involved and neutral toward the underlying technology used to provide a service. Whether a payment is processed through a traditional clearinghouse or a decentralized blockchain ledger, the regulatory focus should remain on the outcome and the risk profile rather than the specific software or protocol employed.
This approach is intended to combat what Enria identified as an "inherent bias toward the status quo." Historically, financial regulations have been written with the assumption that all transactions occur within a centralized, intermediary-heavy framework. Enria’s call for neutrality is a recognition that decentralized finance (DeFi) and distributed ledger technology (DLT) represent a fundamental shift in how value is moved. By adopting a neutral stance, European lawmakers can ensure that the legal framework does not automatically favor incumbent banks simply because they use older, more familiar technologies. This position has the potential to unite disparate factions within the financial world, from radical crypto advocates who demand decentralization to traditionalists who prioritize stability.
The EBA Roadmap and the European Single Market
To move beyond theory and toward implementation, the EBA has developed a comprehensive "Fintech Roadmap." This strategic plan is designed to provide a clear path for digital finance firms to scale their operations across the European Single Market. One of the primary challenges for European startups has been the fragmentation of national regulations; a company successful in Copenhagen often faces entirely different legal hurdles when trying to expand to Paris or Berlin.
The EBA’s roadmap aims to harmonize these rules, providing a "Single Rulebook" that allows fintechs to "passport" their services across the entire European Union. This would theoretically allow a crypto-asset service provider to undergo a single authorization process that grants them access to hundreds of millions of citizens. Enria believes that this unified approach will provide significant benefits to EU citizens by increasing choice, lowering transaction costs, and fostering a more competitive digital economy. The roadmap also includes provisions for monitoring the "perimeter" of regulation, ensuring that as fintech firms grow and potentially take on more bank-like risks, they can be transitioned into more rigorous supervisory categories in a predictable and transparent manner.
Context and Global Regulatory Comparison
Enria’s remarks come at a pivotal moment in the global regulatory timeline. In early 2018, the cryptocurrency market experienced a significant correction following the historic highs of late 2017. During this period, several nations took aggressive stances; China moved to ban initial coin offerings (ICOs) and restrict domestic exchanges, while South Korean officials debated various forms of market bans. In the United States, the Securities and Exchange Commission (SEC) began increasing its enforcement actions against projects it deemed to be issuing unregistered securities.
In contrast to these reactive measures, Enria’s speech reflects a more deliberative, European approach to digital assets. While the G20 and the Financial Stability Board (FSB) have expressed concerns regarding the potential for cryptocurrencies to be used for money laundering or terrorist financing, Enria’s focus remains on the structural integration of technology into the economy. His stance aligns with the broader European Commission "Digital Finance Strategy," which seeks to make Europe a global hub for financial innovation.
Analysis of Implications for the Financial Sector
If Enria’s pragmatic vision is fully adopted, the implications for the financial sector could be profound. For traditional banks, it means a period of protected stability in their core functions of lending and liquidity, but also increased competition in the lucrative payments and e-money sectors. Banks will no longer be able to rely on regulatory barriers to keep fintech competitors at bay in these specific niches.
For the cryptocurrency and fintech industries, Enria’s approach offers a "safe harbor" for innovation. By allowing firms to experiment within a proportionate regulatory framework, Europe could attract a significant amount of human and financial capital from regions where regulations are either too vague or too hostile. However, this also places a burden of responsibility on these firms. To maintain their "intermediary" status and avoid the "enhanced supervision" reserved for banks, they must ensure they do not engage in high-risk maturity transformation or other activities that threaten systemic stability.
Furthermore, the emphasis on technological neutrality may accelerate the adoption of blockchain technology by traditional institutions. If the regulation is neutral, banks themselves may begin integrating DLT to improve their own efficiency, knowing that the technology itself will not trigger additional, unnecessary regulatory scrutiny.
Conclusion and Future Outlook
The speech at Copenhagen Business School serves as a blueprint for a balanced regulatory future. Andrea Enria’s rejection of both total prohibition and total "laissez-faire" suggests that the European Banking Authority is seeking a "Third Way"—one that prioritizes the safety of the financial system without sacrificing the transformative potential of new technologies.
As the EBA continues to roll out its roadmap, the focus will likely shift to the technical details of implementation. How will "proportionate" be defined in practice? What specific metrics will determine when a fintech firm has crossed the line into "bank-like" activity? While these questions remain to be answered through future legislative acts and supervisory guidelines, Enria’s remarks have set a clear, constructive tone. The move toward a technologically neutral, harmonized European market could be the catalyst needed to transition cryptocurrency from a speculative asset class into a functional component of the global digital economy. For now, the industry awaits the formal implementation of these proposals, which many believe could provide the legal certainty required for the next phase of institutional adoption.