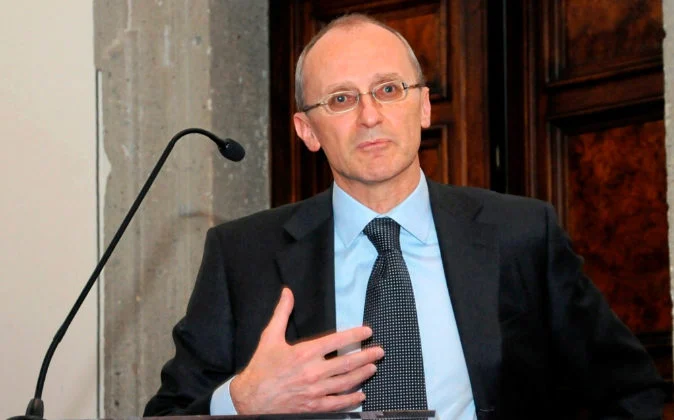
Addressing an audience of academics, students, and financial professionals at the Copenhagen Business School, Andrea Enria, the Chairperson of the European Banking Authority (EBA), has articulated a nuanced vision for the future of financial technology and cryptocurrency regulation. In a departure from the more polarized stances often taken by global financial regulators, Enria cautioned against an overly restrictive approach that could stifle the burgeoning fintech sector, while simultaneously warning that a completely hands-off policy could expose the broader financial system to unmanaged risks. His remarks come at a pivotal moment for the European financial landscape, as the continent seeks to position itself as a hub for digital innovation while maintaining the rigorous standards of its Single Market.
Enria’s critique centered on what he described as a "Manichean" debate currently dominating the regulatory discourse. This dualistic approach typically forces authorities to choose between two extremes: a "regulate and restrict" philosophy or a "laissez-faire" attitude. The former, Enria argued, seeks to prohibit or heavily encumber any financial initiative that deviates from traditional, established banking standards. Such a stance, while intended to protect the status quo, often results in diminishing the capitalization potential of startups and preventing the entry of new, efficient players into the market. Conversely, the "laissez-faire" approach—the idea that all operations should be permitted at the exclusive risk of the participants—fails to provide the legal certainty and protection required to attract long-term, institutional capital. Enria posited that neither extreme serves the public interest or the health of the financial ecosystem.
The Regulatory Perimeter and the Role of Banks
At the heart of Enria’s proposal is the concept of a "regulatory perimeter" that is both flexible and proportionate. He suggested that instead of blanketing all fintech firms with the same heavy-duty regulations applied to systemic banks, regulators should identify which functions are truly critical to financial stability. According to Enria, certain "core" functions must remain strictly within the purview of traditional banks and be subject to "enhanced regulation and supervision." These include the provision of liquidity during crisis situations and the fundamental business of lending, which involves the transformation of maturity and credit risk.
However, Enria made a sharp distinction between these core functions and ancillary services such as payment processing and the issuance of electronic money. He argued that these latter services are not intrinsically linked to the essential safety-net functions of a bank. Therefore, they should be open to a wider array of intermediaries, including fintech startups and cryptocurrency-based firms, without forcing these entities to adopt a full banking license. "An excessive extension of the regulatory perimeter, attracting most fintech firms under the scope of bank-like supervision just because they compete with banks in some market segment, is likely to be a sub-optimal solution," Enria stated. He emphasized that in these specific business areas, the regulatory environment should allow innovators the space to experiment with new products and business practices.
Technological Neutrality as a Guiding Principle
To bridge the gap between innovation and safety, Enria called for a "proportionate and technologically neutral approach" to lawmaking. This principle holds that regulations should focus on the activity being performed rather than the technology used to perform it. By adopting a neutral stance, regulators can combat the inherent bias toward the status quo, ensuring that a blockchain-based payment system is judged by the same risk-based standards as a legacy wire transfer system, rather than being penalized simply for its novelty.
This approach is intended to foster a level playing field. If a fintech firm provides a service that carries the same risk profile as a bank’s service, it should face similar—but proportionate—oversight. If the risk is lower, the regulatory burden should be correspondingly lighter. This prevents "regulatory arbitrage," where firms move to less regulated jurisdictions to save costs, while also preventing "incumbent protectionism," where legacy banks use regulation as a barrier to entry for smaller competitors.
The EBA Fintech Roadmap and the Single Market
To operationalize these views, the European Banking Authority has developed a comprehensive "Fintech Roadmap." This strategic document is designed to allow fintech firms to scale up their operations across the European Union’s Single Market. One of the primary hurdles for European startups has historically been the fragmented nature of national regulations, which often requires a firm to seek separate authorizations in every country it wishes to operate in. The EBA’s roadmap aims to harmonize these requirements, providing a clear path for firms to "passport" their services across all EU member states.
The roadmap focuses on several key areas, including:
- The establishment of a Fintech Knowledge Hub: To facilitate information sharing between regulators and the industry.
- Monitoring of emerging trends: To ensure that the EBA stays ahead of technological shifts like distributed ledger technology (DLT) and artificial intelligence.
- Assessing the perimeter of regulation: Regularly reviewing which activities require a license and which do not.
- Promoting best practices for "sandboxes": Encouraging national authorities to create controlled environments where firms can test innovations under regulatory supervision.
Context: The 2018 Financial Landscape
Enria’s comments arrive during a period of intense volatility and growth in the digital asset space. In the year leading up to his speech, the total market capitalization of cryptocurrencies saw unprecedented spikes, followed by significant corrections. This "boom and bust" cycle has led many global regulators—particularly in Asia and North America—to call for aggressive crackdowns. In the United States, the SEC has increased its scrutiny of Initial Coin Offerings (ICOs), while in China, a total ban on domestic exchanges was implemented.
In contrast, the EBA’s stance, as voiced by Enria, suggests a more moderate European path. While the EBA has previously issued warnings to consumers about the risks of buying virtual currencies—citing the lack of protection and high volatility—Enria’s latest intervention signals a shift toward institutionalizing the sector rather than ostracizing it. This is particularly relevant as European banks themselves begin to explore how DLT can optimize back-office functions and cross-border settlements.
Supporting Data and Economic Implications
The push for a more conducive fintech environment is backed by significant economic data. According to industry reports, fintech investment in Europe reached record highs in 2017, with billions of Euros flowing into startups in London, Berlin, Paris, and Stockholm. However, Europe still lags behind the United States and China in terms of "unicorns" (startups valued at over $1 billion). Analysts suggest that the lack of a unified regulatory framework is a major contributor to this disparity.
By implementing Enria’s proposed "proportionate" approach, the EBA hopes to unlock the potential of the Single Market. If successful, this could lead to increased competition in the financial sector, resulting in lower fees for consumers, faster transaction times, and greater financial inclusion for underserved populations. Furthermore, a clear legal framework for crypto-based activities could attract institutional investors who have previously stayed on the sidelines due to legal and reputational risks.
Reactions from Stakeholders
While the fintech community has largely welcomed Enria’s comments as a "breath of fresh air," the traditional banking sector remains cautious. Representatives from several major European banking associations have argued that while innovation is necessary, the "same risk, same rules" principle must be strictly applied to prevent fintechs from gaining an unfair advantage. They argue that banks carry heavy compliance costs related to Anti-Money Laundering (AML) and Know Your Customer (KYC) protocols, and that any dilution of these standards for new entrants could create weak links in the financial system.
Conversely, blockchain advocates argue that the technology itself can improve compliance. The transparent nature of a public ledger, they suggest, makes it easier for regulators to track illicit flows of funds compared to the opaque systems used in traditional offshore banking. Enria’s call for "technological neutrality" appears to acknowledge this potential, suggesting that the EBA is willing to look at how new tech can meet old regulatory goals more efficiently.
Future Outlook and Implementation
The transition from Enria’s vision to practical implementation will be a complex process involving the European Commission, the European Parliament, and national competent authorities. The EBA does not have the power to write laws—a task reserved for the Commission—but its guidelines and recommendations carry significant weight and often form the basis for future legislation.
As the EBA roadmap moves forward, the industry will be watching closely for specific definitions of "proportionate" oversight. The challenge will be to create a framework that is robust enough to prevent another financial crisis but flexible enough to adapt to technologies that have not yet been invented. For now, Andrea Enria’s pragmatic stance offers a potential third way: a middle ground that seeks to harvest the benefits of the digital revolution without compromising the hard-won stability of the European financial system. This balanced approach may well become the blueprint for other jurisdictions grappling with the disruptive power of fintech and cryptocurrency.