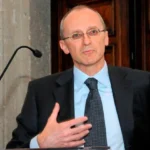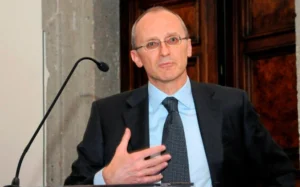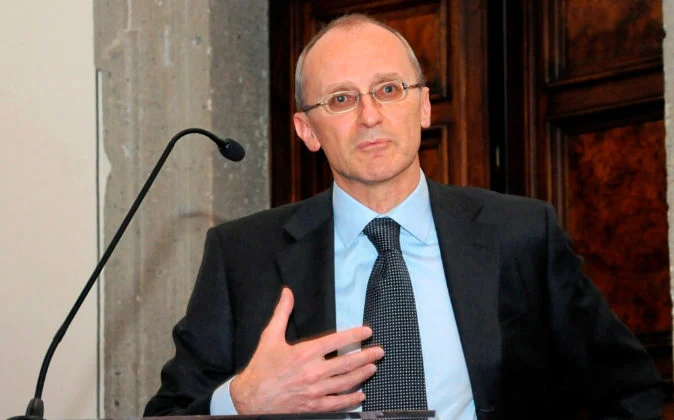
Andrea Enria, the Chairman of the European Banking Authority (EBA), has formally challenged the prevailing regulatory sentiments within the global financial community by advocating for a balanced and "proportionate" approach to the oversight of cryptocurrency and financial technology (Fintech) firms. Speaking at a specialized seminar hosted by the Copenhagen Business School, Enria articulated a vision that moves away from the polarized debate currently dominating the halls of international financial regulation. His remarks come at a critical juncture for the European Union as it seeks to define its stance on digital assets and the burgeoning Fintech sector, which continues to challenge traditional banking models.
Enria’s address focused on the limitations of what he described as a "Manichean approach" to the industry—a binary worldview that forces regulators to choose between two equally flawed extremes. The first position, characterized as "regulate and restrict," seeks to impose traditional, heavy-handed banking standards on all new financial initiatives, effectively stifling innovation before it can reach maturity. The second position, often referred to as "laissez-faire," suggests that the market should be left entirely to its own devices, with all risks borne exclusively by the participants. Enria argued that neither of these paths serves the long-term interests of the European economy or its citizens.
The Pitfalls of Regulatory Extremism
In his detailed critique, Enria explained that the "regulate and restrict" model is fundamentally "sub-optimal" because it creates insurmountable barriers to entry for startups. By forcing a small blockchain-based firm to comply with the same capital requirements and reporting standards as a multinational systemic bank, regulators inadvertently protect the status quo and prevent the capitalization of crypto-based activities. This approach, he noted, limits the competitive pressure necessary to drive efficiency in the broader financial sector.
Conversely, the "laissez-faire" or "let things happen" approach carries its own set of systemic dangers. Enria pointed out that a completely unregulated market increases the inherent risks for consumers and investors alike. Furthermore, a lack of legal clarity and protection actually discourages the entry of institutional capital. Serious investors and traditional financial institutions are often hesitant to enter markets that lack a reasonable level of legal certainty and regulatory oversight. Thus, total deregulation can be just as damaging to a sector’s growth as over-regulation.
Enria’s perspective is rooted in pragmatism, seeking to find a middle ground that allows for the "optimal" level of growth while maintaining the integrity of the financial system. He argued that the goal should not be to bring every Fintech firm under the umbrella of bank-like supervision simply because they compete with banks in specific market segments.
Defining the Regulatory Perimeter
Central to Enria’s proposal is a clear distinction between essential banking functions and peripheral financial services. He suggested that certain core functions—specifically the provision of liquidity during crisis situations and the act of lending—must remain strictly reserved for traditional banks. These activities are the pillars of financial stability and, as such, should be subject to "enhanced regulation and supervision" to prevent systemic collapses.
However, Enria contended that other services, such as payment processing and the issuance of electronic money, do not share the same level of intrinsic risk to the global financial architecture. These areas, he argued, are where innovators should be permitted to experiment with new products, business models, and technological applications. By allowing non-bank intermediaries to handle these functions under a more flexible regulatory regime, the EBA hopes to foster an environment where "Fintech firms can scale up and offer services across the Single Market."
This "proportionate" approach requires lawmaking to be "technologically neutral." This means that regulations should focus on the activity being performed rather than the specific technology used to perform it. Whether a payment is processed via a traditional ledger or a distributed blockchain should be secondary to the regulatory objective of ensuring the transaction is secure, transparent, and legally sound.
The EBA Fintech Roadmap and the Path to Integration
The speech in Copenhagen aligns with the EBA’s broader strategic objectives, as outlined in its "Fintech Roadmap." This roadmap was developed to provide a structured path for the integration of technological innovation into the European financial landscape. The EBA’s goal is to ensure that the regulatory framework is robust enough to protect consumers but flexible enough to allow the EU to remain a global leader in financial innovation.
The roadmap identifies several key priority areas:
- Monitoring the Regulatory Perimeter: Assessing how new business models fit into existing EU law.
- Evaluating Governance and Risk Management: Ensuring that Fintech firms have adequate internal controls.
- Consumer Protection: Promoting transparency and fair treatment for users of digital financial services.
- Cyber Resilience: Addressing the increased security risks associated with digital platforms.
By following this roadmap, the EBA aims to facilitate the "scaling up" of Fintech services across all member states. Currently, many firms face the challenge of navigating 27 different sets of national regulations, which hinders their ability to reach a pan-European audience. Enria’s vision of a unified, proportionate approach would theoretically allow a firm regulated in one EU country to "passport" its services throughout the entire Single Market, significantly reducing compliance costs and fostering cross-border competition.
Supporting Data and Market Context
The push for a more nuanced regulatory framework comes at a time of explosive growth for the Fintech sector. According to data from various European financial monitors, investment in European Fintech reached record highs in the late 2010s, with billions of Euros flowing into startups specializing in payments, regtech, and digital assets. However, the volatility of the cryptocurrency markets—highlighted by the dramatic price fluctuations of Bitcoin and Ethereum—has kept regulators on high alert.
In 2018, the year of Enria’s address, the total market capitalization of cryptocurrencies experienced significant turbulence, dropping from an all-time high of over $800 billion in January to approximately $300 billion by March. This volatility underscored the concerns of those advocating for the "regulate and restrict" approach. Yet, despite this volatility, the underlying blockchain technology continued to see adoption by major financial institutions for back-end processes, lending credence to Enria’s argument for technological neutrality.
Furthermore, surveys of Fintech founders in Europe have consistently cited "regulatory uncertainty" as one of the primary obstacles to growth. By advocating for a clearer, more proportionate framework, the EBA is directly addressing the most significant pain point for the industry.
Global Reactions and Institutional Responses
While Enria’s stance has been welcomed by many in the tech community, it has met with mixed reactions from other regulatory bodies. Some members of the European Central Bank (ECB) have expressed concerns that a "light-touch" approach to payments and e-money could create loopholes for money laundering and terrorist financing. These critics argue that the "technologically neutral" approach must be backed by rigorous Anti-Money Laundering (AML) and Know Your Customer (KYC) protocols that are just as stringent as those applied to traditional banks.
In the United States, the regulatory environment remains similarly divided, with the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) often overlapping in their jurisdictions over digital assets. Enria’s proposal for a clear "regulatory perimeter" is seen by some international observers as a potential model for the U.S. and Asian markets to emulate in order to provide the legal clarity that global investors crave.
Industry advocacy groups, such as Blockchain for Europe and the European Fintech Association, have largely supported Enria’s comments. They argue that a "one-size-fits-all" regulatory model is the greatest threat to Europe’s digital sovereignty. They emphasize that if the EU becomes too restrictive, talent and capital will simply migrate to more innovation-friendly jurisdictions like Singapore or Switzerland.
Analysis of Long-Term Implications
If the EBA successfully implements the vision articulated by Andrea Enria, the long-term implications for the European financial sector could be profound. A proportionate regulatory regime would likely lead to a more diverse financial ecosystem where traditional banks coexist with agile Fintech startups. Banks would continue to serve as the bedrock of the economy, managing high-risk functions and providing systemic stability, while Fintech firms would drive innovation in consumer-facing services and operational efficiency.
Moreover, this approach could accelerate the adoption of a "Digital Euro" or other central bank digital currencies (CBDCs). By establishing a clear legal framework for electronic money and payments now, the EU is laying the groundwork for the next generation of sovereign digital infrastructure.
However, the success of this plan hinges on the ability of regulators to remain "proportionate" in practice, not just in theory. There is always a risk of "regulatory creep," where the perimeter slowly expands to encompass more activities under the strictest rules. Maintaining the balance between safety and innovation will require constant dialogue between the EBA, national regulators, and the Fintech community.
Conclusion
Andrea Enria’s call for a departure from the binary "regulate or ignore" mindset marks a significant evolution in the European Banking Authority’s philosophy. By championing a middle path that prioritizes technological neutrality and proportionate oversight, Enria is attempting to bridge the gap between the traditional financial world and the digital future. While the implementation of such a framework will take time and require extensive cooperation across the EU, the proposal offers a roadmap for a more competitive, innovative, and stable European financial market. The eyes of the global financial community will undoubtedly remain on the EBA as it attempts to turn this pragmatic vision into a regulatory reality.