The digital asset industry faced a significant legislative setback this week as the United States Senate failed to advance the Digital Asset Market Clarity Act, a piece of legislation widely viewed as a potential cornerstone for regulatory certainty in the American crypto market. However, Matt Hougan, the Chief Investment Officer at Bitwise Asset Management, argues that the market’s underlying momentum remains robust. According to Hougan, the failure of the bill, often referred to as the CLARITY Act, represents a mere "speed bump" rather than a terminal "roadblock" for the ongoing cryptocurrency bull market. His assessment comes at a time of heightened volatility, where investors are weighing the impact of political gridlock against the backdrop of increasing institutional adoption and shifting regulatory strategies from federal agencies.
On Tuesday, the Senate held a crucial vote on cloture for the Digital Asset Market Clarity Act. The motion required 60 votes to overcome a potential filibuster and move the legislation toward a final floor vote. The tally ultimately landed at 49 to 50, falling significantly short of the supermajority needed. The rejection of the bill underscores the deep partisan and philosophical divisions within Congress regarding how to categorize and regulate digital assets. Despite this legislative impasse, Hougan maintains that the market has already "priced in" the likelihood of such an outcome, noting that Bitcoin’s price trajectory over the summer diverged sharply from the legislative prospects of the bill.
Market Resilience and the Decoupling from Legislative Outcomes
A primary pillar of Hougan’s argument is the historical performance of Bitcoin during the period when the CLARITY Act’s chances of passage were actively declining. To support this, Bitwise tracked the odds of the bill becoming law via Polymarket, a decentralized prediction market platform. In early July, the perceived probability of the CLARITY Act passing this year stood at approximately 39%. By early September, those odds had plummeted to just 18%.
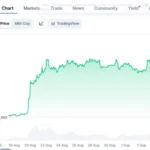
During this same window, Bitcoin exhibited remarkable strength. On July 1, the premier cryptocurrency was trading at approximately $57,950. By September 4, the price had surged to surpass the $80,000 threshold. Hougan points to this inverse correlation as definitive proof that the current bull market is driven by factors far more fundamental than a single piece of legislation. "If the bull market depended on Clarity’s passage, you would have expected falling odds to mean falling prices," Hougan noted in a recent memo to investors. The fact that the asset class appreciated significantly while the bill floundered suggests that liquidity, institutional inflows, and technological milestones are currently the primary drivers of value.
While Bitcoin did experience a roughly 4% decline immediately following the Tuesday vote, market analysts attribute this dip to a combination of factors. Beyond the legislative news, the broader financial markets were grappling with renewed concerns over oil prices and the Federal Reserve’s trajectory regarding interest rates. The crypto market’s reaction, therefore, appeared to be a standard response to macro-economic pressure rather than a specific rejection of the crypto industry’s future in the absence of the CLARITY Act.
A Chronology of Institutional Expansion
One reason for the market’s perceived "decoupling" from Washington’s legislative cycle is the relentless pace of institutional integration. Throughout the summer of 2024, as the Senate debated the merits of the CLARITY Act, major financial institutions continued to deploy capital and launch products in the digital asset space. This trend suggests that the private sector is moving forward with or without a comprehensive federal framework.
In July, the popular trading platform Robinhood reached a major milestone by launching the mainnet of its own proprietary blockchain. This move signaled a shift for the company from a mere brokerage to a participant in the underlying infrastructure of the decentralized web. Shortly thereafter, Morgan Stanley, one of the world’s largest wealth management firms, expanded its crypto offerings by launching Ethereum and Solana exchange-traded products (ETPs). This followed the highly successful launch of Bitcoin ETPs earlier in the year, further normalizing digital asset exposure for high-net-worth clients.
Furthermore, the Depository Trust & Clearing Corporation (DTCC), which provides the infrastructure for the global financial markets, successfully completed production trades using tokenized securities. These developments represent a structural shift in how traditional finance views blockchain technology. For many institutional players, the focus has shifted from "if" they will use blockchain to "how" they will use it to optimize settlement times and reduce costs. Hougan argues that these "on-the-ground" advancements provide a more stable foundation for a bull market than the volatile and often unpredictable nature of congressional lawmaking.
The Shift Toward Agency-Led Rulemaking
With the CLARITY Act stalled in the Senate, the regulatory spotlight is expected to shift back toward the executive branch agencies, specifically the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC). Both agencies have indicated a willingness to use their existing statutory authority to bring order to the digital asset markets, albeit through different philosophies.
In August, the SEC proposed "Regulation Crypto Assets," a framework designed to clarify how certain investment contracts involving digital assets should be treated under existing securities laws. While the proposal has faced criticism from some industry advocates for being overly restrictive, it represents an attempt by the agency to create a structured path for compliance.
The SEC took an even more significant step on Thursday, just two days after the failed Senate vote. The agency approved a temporary "Innovation Exemption," which allows qualifying trading venues to facilitate the on-chain trading of tokenized U.S. stocks under specific conditions. SEC Chair Paul Atkins explicitly linked this move to the legislative vacuum left by Congress. By providing a pathway for tokenized securities, the SEC is effectively moving to capture the "tokenization" trend within its regulatory perimeter, ensuring that the U.S. remains a viable hub for financial innovation despite the lack of new laws.
Similarly, CFTC Chair Michael Selig has signaled that his agency is prepared to move forward with market structure rules for digital assets. The CFTC has long sought broader authority over crypto spot markets, a power that the CLARITY Act would have formally granted. In the absence of that bill, Selig suggests the CFTC will lean on its existing authority to police fraud and manipulation while pushing for more transparent market operations.
The Durability Gap: Legislation vs. Regulation
Despite his optimistic outlook on the bull market, Hougan did acknowledge a critical distinction between legislative clarity and agency rulemaking. Legislation, once passed into law, provides a durable and permanent framework that is difficult to overturn. It provides the "gold standard" of certainty that large-scale institutional investors often require before committing massive amounts of capital.
In contrast, agency rules are subject to the "pendulum of politics." A framework established by a current administration can be significantly altered or entirely reversed by a future administration with a different regulatory philosophy. This lack of permanence remains a lingering concern for the industry. Furthermore, without a new act of Congress, the CFTC still lacks the comprehensive authority it needs to oversee the entirety of the crypto spot market, leaving a fragmented landscape where different assets fall under different jurisdictions.
Hougan’s view is that while the industry would prefer the permanence of the CLARITY Act, it is more than capable of thriving under agency-led "Regulation by Rulemaking" or "Regulation by Enforcement." The adaptability of crypto firms, combined with the global nature of the asset class, means that a lack of progress in Washington does not necessarily equate to a lack of progress for the technology or the market.
Broader Implications and the Path Forward
The failure of the CLARITY Act highlights a broader trend in the 2024 political landscape: digital assets have become a significant, albeit polarizing, political issue. The 49-50 vote suggests that while there is nearly half-support in the Senate for a pro-innovation framework, the hurdle for a 60-vote consensus remains high.
Looking forward, the crypto industry is likely to focus its efforts on the upcoming election cycle, hoping to seat a Congress and an administration more amenable to formalizing the digital asset framework. In the interim, the market’s attention will likely remain on macroeconomic indicators—such as inflation data and employment reports—and the continued adoption of blockchain technology by Wall Street.
Matt Hougan’s analysis serves as a reminder that the cryptocurrency market has matured significantly since the last bull cycle. In previous years, a legislative failure of this magnitude might have triggered a prolonged "crypto winter." Today, however, the ecosystem is bolstered by massive ETP inflows, a growing suite of institutional products, and a regulatory environment that, while messy, is increasingly active.
In conclusion, the CLARITY Act’s failure is undoubtedly a setback for those seeking a unified federal policy. However, as Bitcoin continues to trade at historic highs and major financial institutions deepen their involvement in the space, the "speed bump" described by Hougan appears to be one that the market is well-equipped to navigate. The shift toward agency-led rules may provide the temporary bridge needed until a more permanent legislative solution can be reached, ensuring that the current bull market trend remains intact for the foreseeable future.